Roth IRA - A Really Stupid Idea

Just ran across this, if anyone's interested.

https://www.marketwatch.com/story/t...to-and-two-to-avoid-11617819803?siteid=yhoof2

Several years ago, I was talking to a gentleman outside a supermarket. He was in South Florida temporarily, while undergoing a medical treatment. Then he said, "Normally, we spend out winters in Taiwan. The weather is similar and it's much cheaper. The only catch is that the locals prefer you spoke Chinese". My reply was, "Well, where do you spend summers?". He says, "Brest". That forced me into a double take. "Brest, France or Brest, Belarus?". "Brest, Belarus. My wife is from there".

Belarus was experiencing much less turmoil then bit I hark to my youth in our summer home and think how much I enjoyed it.

Not everyone's cup of tea, clearly, but can be an option for some.
I've seen similar articles about how to save money, but when you think about it, it's not feasible. Most people in their later years don't want to move to a foreign country that they don't know anyone or speak the native language just to save money. The story you related isn't the case either because he was born in Belarus. When you're young, don't have any ties, and want to explore the world sure, most people at retirement age care about their ties to their family and friends. It's one thing to spend the winters in Costa Rica it's another to permanently move there.
 
Actually, I was born in Belarus, then part of the USSR. The guy was an American.

But I agree in general. Beach living in Florida can be expensive but moving a few miles inland and away from the heavily populated Miami-Fort Lauderdale territory can be far more budget friendly.

I have several friends in California and I have brought up Florida retirement to them, as they're hitting their 60's. One prefers Arizona because he has a lot of family in the LA area. The other is agnostic but can afford his near beach side in San Diego. Off Zillow, I'd say that the best buys are in the Cocoa Beach and Destin areas.
 
Well, Paul - doggone it, thanks for ruining my retirement. My wife & I both have money stuck in a Roth IRA. Guess we're screwed. :angry:
One of the reasons we were told it was a good way to go - so many years ago - was that our son had just been born - and it was another way to save for his college. I believe the reason being you can withdraw any principal amount without a penalty before retirement age. That son will start college this fall - and we are still a few years from retiring... although you have me wondering now if I should start making calculations... perhaps I'm closer to retiring than I thought I was. :beer:
 
... perhaps I'm closer to retiring than I thought I was. :beer:

Well beers to that! Yes, perhaps so.

Retiring is an eye opener like any life event. It's so bloody frustrating to gain all your wisdom when you don't need it. Before retirement I wondered if it was really going to work financially; were my calculations correct? Trust them. They are correct. I think the thing that made me question my estimates was how little money we really needed. It made us wonder where all the money was going before retirement. But I had had enough of the grind and wanted to enjoy life so I decided to take the plunge and hope for the best. Before I retired other retirees told me the same thing I am tell you; it's going to be ok and you won't need as much as you think. :beer:
 
Today's headline from Barron's - "Early Retirement is Not as Good as it Sounds. Advisors Need to Persuade Clients To Keep Working."

Oh man. I bust a gut when I read stuff like this. Get ready for an urgent call from your financial advisor who just read this article. No, I don't know what it says. But who cares. Talk about baiting your clicks. This one is a whopper.

Hey, if you love your job, by all means don't quit.
 
... diversify buy and hold quality assets for the long term.
And that my friends is the only advice anyone should give or listen to. That is the best investment sentence there is. Wade into what Peter said. Do it.

We all know the story about the poor people who worked at Enron. Those poor folks really got sold a story. I also knew a guy that work at AT&T Bell Labs back in the day when they were a big deal. He put all his retirement in to AT&T stock. AT&T stock back then was the rock of Gibraltar. Nothing was more solid than AT&T stock. Then the company fell apart, Bell labs became a shell, he lost all his money and he is now in his 70's still working.

You can't take too many steps to diversify. Don't put all your money with one brokerage. No matter what size the company, it can either be a Ponzi scheme or go default (think Lehman brothers and Bernie Madoff). I think the least safe place to put your money is with a local guy. You know, the friend of the family; the church member who has a solid reputation. If you ever watched those old American Greed shows, you know that there is a Ponzi scheme brewing in every town in America. Time and time again, the trusted guy with the solid reputation ends up running a Ponzi scheme that ruins people's lives.

Spread the money around.
 
My retirement strategy 1. Pick six 2. Slip and fall 3. Someone always needs a green card 4. Keep five grand in sock drawer for Guatemala backwater beach bar 5. Cruise line gentleman companion 6. The world always needs dishwashers
 
All-in-all I think you have a solid portfolio. It's well diversified, lots of options, low risk, except for number 2. I'd say you're in good shape.
 
Yep number 2 is a question but I have cat like reflexes and really enjoy wearing a neck brace. Lots of opportunities on my daily route Receiving snacks from the folks passing out samples foods in the grocery , free cofffee popcorn and hot dogs at the local Lexus dealer. FYI the rotesiere chicken at Costco is not put out as samples, learned that recently and repeatedly.
 
Here's a 2023 update for this topic. I finished my 1040. Here are the results of taxes paid on IRA withdrawals. What is new this year is that I drew $30,000 out, $10k more than previous years. The result is that we owe $1089 in taxes on an income of just under $82k. That's a tax of 1.3% or if you apply the tax against just the $30k IRA withdrawal, it is a tax of 3.6%. Even if you don't take the break social security offers, that is, the $82K fully taxed (which is actually $56.4k after the senior married filing joint standard deduction), the tax is only 7.6%.

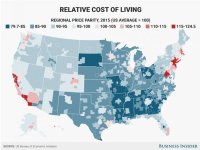
Remember that $82k is all in pocket. Minor federal income tax, no social security deduction, no workmen's comp, no contributions to retirement, no debt interest. We live in one of those red areas on the map and that makes for a comfortable living.

This is just information. It's stuff I wish I had when I was wondering about retirement.

cost of living map.jpg
 
Paul, can I ask what makes up the 82K in "income"? If you are retired, how do you bring in $52,000 (assuming social security is part of the $52,000).

I think your initial argument kind of falls apart as the number go higher. If you withdrew $50,000 from the IRA you would pay more etc... Roth would still be $0. I will state again, once RMDs kick in you will be forced to withdraw more than you want to. And pay the tax... But, the Roth is not a direct comparison as it has lower initial contribution limits per year. So it is hard to really build up a large Roth IRA.

Not that paying the tax is so bad from my view. It is part of the system. The important thing is to save & plan. I am no fan of the IRA as you or your heirs will end up paying the tax in the end anyway. It is only tax deferred.
 
The other day, I operated an audio mixer for a panel of financial experts speaking to a group of high schoolers about investing.
When the session was over, and I was retrieving the mics, I asked one of the panelists a few questions.
  1. Should I primarily invest in overseas companies during a USA recession?
  2. Is there a recommended ratio of USA to overseas investments?
  3. Would you recommend a traditional IRA or a Roth IRA?
This guy looked old enough to be retired, but he didn't have specific answers, and referred me to other younger panelists. I understand that there aren't necessarily two second answers to those questions, and that there are different areas of financial expertise, but there should be at least some crossover knowledge of other areas, particularly after a life's career in that field.

I had to run to another session, and didn't get a chance to ask the other panelists my questions, so feel free to throw in your two cents.

My day job is as an AV Tech, and I'm constantly learning about IT, even though it isn't my field, there's more and more crossover and blurring of the lines these days, so you have to keep learning, and I just expect a highly educated person with 40+ years of professional, and life experience to be more knowledgeable than me.
 
Paul, can I ask what makes up the 82K in "income"? If you are retired, how do you bring in $52,000 (assuming social security is part of the $52,000).

I think your initial argument kind of falls apart as the number go higher. If you withdrew $50,000 from the IRA you would pay more etc... Roth would still be $0. I will state again, once RMDs kick in you will be forced to withdraw more than you want to. And pay the tax... But, the Roth is not a direct comparison as it has lower initial contribution limits per year. So it is hard to really build up a large Roth IRA.

Not that paying the tax is so bad from my view. It is part of the system. The important thing is to save & plan. I am no fan of the IRA as you or your heirs will end up paying the tax in the end anyway. It is only tax deferred.

Good questions. To your first question - Of the $82k, $30k was IRA withdrawal and $52k is social security. The $52k is my SS plus my wife, who gets to take advantage of spousal benefits. She gets half the SS I do instead of what she actually earned. (Is there any wonder why SS is going broke?) She gets 3x what she earned for no reason other than somebody came up with that rule. But that rule has ended, but she is grandfathered.

Let's take a look an RMDs. There's a few ways to run the numbers. How do you want to look at it?

A - Roth and non-Roth both put maximum $6000 in every year. Non-roth invests the money they didn't get taxed in the Dow Index
B - Roth puts in less money in IRA because they had to pay tax. So Roth puts in xx dollars less than traditional IRA, who puts in the $6000 max.
 
Last edited:
......
My day job is as an AV Tech, and I'm constantly learning about IT, even though it isn't my field, there's more and more crossover and blurring of the lines these days, so you have to keep learning, and I just expect a highly educated person with 40+ years of professional, and life experience to be more knowledgeable than me.

My impression over 40+ years is that they are all full on nonsense. They all seem to spew pablums without really having solid work behind what they say. I wouldn't listen to advice from any of them. Do your own reading. No one has a crystal ball.
 
My impression over 40+ years is that they are all full on nonsense. They all seem to spew pablums without really having solid work behind what they say. I wouldn't listen to advice from any of them. Do your own reading. No one has a crystal ball.

That's why I don't want to pay a financial advisor. Bad advice costs just as much as good advice. And every time I trust an expert to give me an evaluation (a car mechanic, a home inspector), I regret it. You have to do as much research as you can.

That being said, what little I've learned about retirement investing is fiendishly complicated. And I'm just talking about which investment vehicles to use, not about where to put the money.

But the basic sense i get is that it only makes sense to go Roth if you think your income will be higher in retirement than while you're working. (There's an added wrinkle which is if you expect tax rates to be higher in the future than now, though no one can know for sure.)
 
The other day, I operated an audio mixer for a panel of financial experts speaking to a group of high schoolers about investing.
When the session was over, and I was retrieving the mics, I asked one of the panelists a few questions.
  1. Should I primarily invest in overseas companies during a USA recession?
  2. Is there a recommended ratio of USA to overseas investments?
  3. Would you recommend a traditional IRA or a Roth IRA?
This guy looked old enough to be retired, but he didn't have specific answers, and referred me to other younger panelists. I understand that there aren't necessarily two second answers to those questions, and that there are different areas of financial expertise, but there should be at least some crossover knowledge of other areas, particularly after a life's career in that field.

I had to run to another session, and didn't get a chance to ask the other panelists my questions, so feel free to throw in your two cents.

My day job is as an AV Tech, and I'm constantly learning about IT, even though it isn't my field, there's more and more crossover and blurring of the lines these days, so you have to keep learning, and I just expect a highly educated person with 40+ years of professional, and life experience to be more knowledgeable than me.

1) No, your investing should be for a longer time horizon like 20-40 years. Recessions come and go but quality companies/investments continue to grow.
2) No, that is up to your desire to put money in overseas markets. Many believe both ways. If you are unsure, the US is about the best game in the world.
3) Both serve a goal in creating an incentive to save and invest your money for retirement. IRA's are tax wrappers for your savings. I say savings because you do not have to be "invested" to be in an IRA. You can stay 100% cash inside an IRA. They are like wormholes for your retirement money. That money is just deemed to be tax deferred (traditional IRA) or free of further tax on any gains once the initial tax is payed (ROTH).
4) *Investment Advice* - Put your money into an S&P 500 index fund like the Vanguard S&P 500 ETF and contribute to it on a monthly basis. Small purchases each month allow you to buy in all types of market conditions. Reinvest all of the dividends along the way and see where it ends up in 20-40 years. It really can be as simple as that.
 
Good questions. To your first question - Of the $82k, $30k was IRA withdrawal and $52k is social security. The $52k is my SS plus my wife, who gets to take advantage of spousal benefits. She gets half the SS I do instead of what she actually earned. (Is there any wonder why SS is going broke?) She gets 3x what she earned for no reason other than somebody came up with that rule. But that rule has ended, but she is grandfathered.

Let's take a look an RMDs. There's a few ways to run the numbers. How do you want to look at it?

A - Roth and non-Roth both put maximum $6000 in every year. Non-roth invests the money they didn't get taxed in the Dow Index
B - Roth puts in less money in IRA because they had to pay tax. So Roth puts in xx dollars less than traditional IRA, who puts in the $6000 max.

Thanks. You have a great retirement situation. Congratulations.

I see the Roth as a vehicle designed for when you are younger, and earning. You pay the tax bill outside of the amount that goes into the Roth. So in your example the Roth would also have $6,000 placed.

I see the traditional IRA as an incentive by the government to invest for their retirement. It also serves as a tax windfall for the government as they always get what is due to them in the end. So while it looks like you are killing it growing up money tax free, as the years tick by, they come a calling and the taxable amount is then much greater than when you started. The RMDs increase each year and in your years of smaller income (not so small in your case ;) the pain of a larger tax bill might be worrisome to many. That is main downside I see to a Trad. IRA.

The Roth would not suffer form this worry as the growth that takes place does not come with a tax bill on the other side. But, given the contribution limits are lower on a Roth, it is difficult to really stack up a large amount in a Roth. Large enough to really have some tax pain.

In many ways, thinking about taxes too much in investing is the tail wagging the dog. In the end, having a large amount of investment gains and a large amount of money are good 'problems' to have... The important thing is to invest and create wealth. What you do with it is secondary.
 
Back
Top