Retirement Information - Things that may help you

By the way, the IRS offers a direct tax form and free file system. Do not confuse this with the free file the IRS advertises from tax software providers. Those suck. Avoid at all cost. It's not easy to find because the free file offers from the tax software companies show up first.

It doesn't put your through the onerous question and answer sequence that tax software puts you through, which I find aggravating. Sure, it's great if your not sure about what you are doing. But if you know what you want to file, the IRS fillable forms is pretty nice. It presents fillable 1040 and other forms, it does the math, it does a preliminary check of your filing and you file for free directly to the IRS.
https://www.freefilefillableforms.com/home/default.php

California has an ever better online system It pulls your information from your past filings, prefills the forms in with what it already knows, takes care of those ridiculously long 'exceptions from your federal filing' forms and files for free. Very nice. I highly recommend it to Californians.

https://www.ftb.ca.gov/file/ways-to-file/online/calfile/index.asp

ok Paul, now you're just rubbing salt in the wound. I can accept that you pay no taxes. but I don't want to hear about how easy it is for you to file
 
I used to work with a shooter in Boston who told me, when I was in a jam, that he couldn't help with a two-camera shoot the next day because it was his daughter's 2nd birthday. That told me everything I need to know about his priorities and he was the last person I ever called next time. There is a time for work, which often is beyond our control. Make hay while the sun shines. On the other hand, quality family time can come the next day or whatever. Do you think a two-year-year old can read a calendar to know if it is her birthday or not? Trust me, your family will be more secure, safer, and comfortable the more you earn.

Making work a priority is making the family a priority. Think about it.

My feeling about this has changed over the years. I made work a priority for the past 40 years and while it has had its benefits, this way of thinking also kept me out of having a family in the first place. I missed a lot of friend's weddings, trips and other life experiences that I wish I had now that it's too late. I've also seen way too many marriages destroyed by this industry (the long hours, working out of town for extended periods). Those people were working to make their family comfortable, and the family ended up torn apart as a result. It's nice if you can have it all in this business, but for many people that is an elusive goal. The concept of balance is a moving goal post. What might make sense to the breadwinner might foster resentment in the spouse or children, even if it defies logic.

The most important takeaway I got from the anecdote above (the daughter's 2nd birthday one): he probably should have just told you he wasn't available, and then you wouldn't have moved him down your list. I have a different management style myself, but this is a good reminder that exposing our personal life in a business environment (including political and social preferences) can become a liability.
 
ok Paul, now you're just rubbing salt in the wound. I can accept that you pay no taxes. but I don't want to hear about how easy it is for you to file

That's what I'm here for Abe. Let's face it, I'm not really here to help anyone with these posts. I'm here to make all of you feel miserable.
 
The Federal Debt keeps growing because government keep devaluing the dollar by printing more currency, and spending like a drunken sailor.

Your Social security payments aren't even a rounding error.

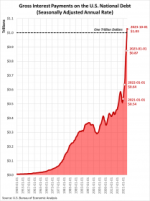
Gross_Interest_Payments_on_US-National_Debt_1949_01_2023_10.png
 
The Federal Debt keeps growing because government keep devaluing the dollar by printing more currency, and spending like a drunken sailor.

Your Social security payments aren't even a rounding error.


ugh. the interest rate on federal debt has more than doubled since 2020 in tandem with the sharp increase in the Fed rate.

M2 peaked in March 2022 and has modestly declined since then: https://fred.stlouisfed.org/series/M2SL

take your sloppy analysis elsewhere. Tom Roper had a much better read on the situation earlier in this thread
 
The Federal Debt keeps growing because government keep devaluing the dollar by printing more currency, and spending like a drunken sailor.

Your Social security payments aren't even a rounding error.


I don't follow, SS and Medicare are 35% of the budget while the debt interest is 13%.

Yes, ugh Abe, just a couple years ago, it was 8% of the budget. If we thought Greece's collapse was bad, if the US collapses, the world will collapse. It will be ugly.
 
Yes, ugh Abe, just a couple years ago, it was 8% of the budget. If we thought Greece's collapse was bad, if the US collapses, the world will collapse. It will be ugly.

If you see any deer staring at you from the woods, or witness a hundred white Teslas piling up on the freeway, or oil tankers slamming into the beach, or Julia Roberts dancing awkwardly in your basement, you'll know the end is nigh. In fact, we might look back and realize the cargo ship taking down the bridge in Baltimore was the first sign.
 
If you see any deer staring at you from the woods, or witness a hundred white Teslas piling up on the freeway, or oil tankers slamming into the beach, or Julia Roberts dancing awkwardly in your basement, you'll know the end is nigh. In fact, we might look back and realize the cargo ship taking down the bridge in Baltimore was the first sign.

That's an interesting thought. I wonder when some young lad, sitting in his dark basement bedroom, will get the idea to hack Tesla's self driving feature and set up a wi-fi mesh network that takes them all careening off the roads.
 
Last edited:
I don't follow, SS and Medicare are 35% of the budget while the debt interest is 13%.

Yes, ugh Abe, just a couple years ago, it was 8% of the budget. If we thought Greece's collapse was bad, if the US collapses, the world will collapse. It will be ugly.

I agree that US debt growth and interest payment growth is unsustainable. I completely disagree with his analysis. Specifically, interest payments have recently ballooned mostly because of increases in interest rates, not increases in the principal. And if rates go back down, the payments will go back down.

And if Greece were not in the EU and had their own currency, they would have had a much, much easier time handling that situation. I assure you, we will not be Greece.

This is a simple tax receipts to expenditures ratio issue. Nothing more, nothing less.

BTW our military spending is over $1.5T a year when you count spending on veterans and our nuclear weapons program.

There are at least 11 countries with a higher debt to GDP ratio than us, including Japan, Italy, and Singapore. Spain, France, Canada, and the UK are not far behind us, each with debt greater than 100% of GDP.
 
Last edited:
I was going to comment, but that would take us off topic and into well worn discussions and it would get political.
 
Last edited:
I was going to comment, but that would take us way topic and into well worn discussions and it would get political/

Darn. I was sure we were about to solve America's debt

Fun fact: the US never paid off its WWII debt. It just became increasingly irrelevant as the economy grew. Macroeconomics is fundamentally different from microeconomics. And most people know something about the latter but nothing about the former.

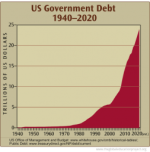
wealth_us-gov-debt-1940-2020.png


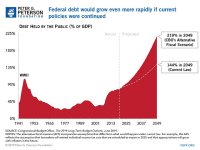
how-the-national-debt-grew-in-2019-chart-1.jpg

The key difference is that they stopped borrowing after WWII. But with the exception of Clinton, every president since Reagan has borrowed profusely.
 
Last edited:
Doesn't change that inflation in 2021 was 4.7%. In 2022, the year Congress passed the Inflation Reduction Act, it was 8.0%, in 2023 it was 4.1%. The IRA was an $891B spending spree on climate change initiatives and Affordable Care Act subsidies.
Between 2012-2020 inflation was never higher than 2.4%, and had been as low as 0.1%.

It's a perfect example of why I said Orwell's 1984 came true, ministry of "Truth," yeah.

Yeah obviously the title of the bill was misleading and had little to do with the bill. That happens all the time. (Although there were a couple of price-controlling measures in it.)

World inflation rate for 2022 was 8.27%, a 4.8% increase from 2021. World inflation rate for 2021 was 3.48%, a 1.55% increase from 2020.
World inflation rate for 2020 was 1.93%, a 0.28% decline from 2019.
World inflation rate for 2019 was 2.21%, a 0.23% decline from 2018.
https://www.macrotrends.net/global-...tion rate for 2022,a 1.55% increase from 2020.
 
Speaking of retirement planning......

I had one question about retirement planning. I'm sure I can find a wealth of info on this elsewhere but I'd love your 2 cents.

Regarding spending estimates -- the one thing I can see going up is medical expenses. Obviously, some or most or all of that might be covered by Medicare... but did you plan for expenses that you'll need to cover out of pocket? And how did you estimate those?
 
I've made no contingency plans for health coverage. From my job to COBRA coverage to Obamacare (when COBRA expired after 18 months but too young for Medicare) to Medicare, I've had the same provider. It was smooth transfer all the way. When I fractured my hip under Medicare, the medical cost was $65,000. My total cost was $540 which was the copay for 3 days in the hospital ($450) plus some other small fee. Everything was covered by the provider including the $2000 fire department ambulance ride from my house to the local hospital that is 3 miles away. No paperwork, no fuss. Just one little bill from the provider asking for $540. Easy peasy. I don't pay the bills, but I think Medicare is somewhere around $180/mo. It keeps going up like anything else. But it was certainly cheaper than my company insurance.

By the way, morphine and fentanyl are really disappointing. I guess some of us are made for opioids and some are not. Both made me slightly nauseous and provided me with no pleasant effects. I found oxycodone to be effective and slightly nice, but not nice enough to use it for anything but pain. A beer is better.

There is no dental insurance. Yes, companies offer it, but it will cost more than paying the dentist directly. My dentist warned me when I tried it. He was right. Not only that, but it seemed only questionable practices accepted the dental insurance. My wife puts some of the SS money into a fund for stuff like this. So there is always money laying about to cover our dental visits and things like the water well breaking or a hot water heater. The thing is we don't really need that sort of fund, but it makes her happy to have a bin at the bank that is the place to pull money out that is not a regular expense. When we want something expensive (vacation, gazebo, other toy) it comes out of that fund).

Long term care - well, that's a problem. I don't have any coverage for that.
 
Last edited:
I've made no contingency plans for health coverage. From my job to COBRA coverage to Obamacare (when COBRA expired after 18 months but too young for Medicare) to Medicare, I've had the same provider. It was smooth transfer all the way. When I fractured my hip under Medicare, the medical cost was $65,000. My total cost was $540 which was the copay for 3 days in the hospital ($450) plus some other small fee. Everything was covered by the provider including the $2000 fire department ambulance ride from my house to the local hospital that is 3 miles away. No paperwork, no fuss. Just one little bill from the provider asking for $540. Easy peasy. I don't pay the bills, but I think Medicare is somewhere around $180/mo. It keeps going up like anything else. But it was certainly cheaper than my company insurance.

By the way, morphine and fentanyl are really disappointing. I guess some of us are made for opioids and some are not. Both made me slightly nauseous and provided me with no pleasant effects. I found oxycodone to be effective and slightly nice, but not nice enough to use it for anything but pain. A beer is better.

There is no dental insurance. Yes, companies offer it, but it will cost more than paying the dentist directly. My dentist warned me when I tried it. He was right. Not only that, but it seemed only questionable practices accepted the dental insurance. My wife puts some of the SS money into a fund for stuff like this. So there is always money laying about to cover our dental visits and things like the water well breaking or a hot water heater. The thing is we don't really need that sort of fund, but it makes her happy to have a bin at the bank that is the place to pull money out that is not a regular expense. When we want something expensive (vacation, gazebo, other toy) it comes out of that fund).

Long term care - well, that's a problem. I don't have any coverage for that.

I think medicare/medicaid covers long-term care after you go broke is the idea? and are you talking about cancer treatments when you talk about long term care? or is that just covered by medicare? what would you say isn't covered by medicare?
 
Medicare does not cover long term care. Long term care is not cancer treatments. It's when you become decrepit and can no longer take care of yourself. There are state programs for people that are broke.
 
Medicare has 4 parts:

Part A: Hospitalization, known as "free Medicare." $0 cost.
Part B: Outpatient, doctor visits, clinics, lab work, radiology. Optional, this costs $174 per month.
Part D: Drugs, This coverage is optional, Medicare doesn't pay for drugs.

Medicare only pays 80%, patient pays 20%. This is important, heart or cancer treatments can run in the millions, in fact it's unusual if they don't.

Private insurers offer Medigap, which can help with the parts that Medicare doesn't pay, by filling the gap.

Part C: This is called Medicare Advantage, private plans reimbursed by Medicare.

You either buy Parts B and D from government Medicare, and supplement it with a Medigap policy from the private insurers; or buy part B from government Medicare and Part C from a private insurer. Part C usually covers the copays and deductibles and most drugs, so you don't need Medigap or Part D. Many Part C plans usually have $0 monthly premium, and offers additional benefits like dental, vision, in-home care, rehab, health club membership benefits, etc. But the major benefit is that instead of potentially getting stuck with 20% of the bill as with regular Medicare, there is an out-of-pocket maximum such as $3,500 / year that you could be responsible for in a worst case. They will pay 100% after your out of pocket maximum has been met.
 
Back
Top