Retirement Information - Things that may help you

Paul F

Veteran
Picking up where I left off in my "Roth IRA, a really stupid idea" thread, here is the update on our 2023 tax return that may help you understand what retirement is like. It's a whole lot better than you might imagine.

For 2023, our income was $78k. That's $56k of social security, $20k IRA withdrawal, and a bit of bank interest. Federal taxes on that is $0. California tax is $0.

Yes, contrary to popular belief, the rich aren't the only ones with big loopholes. Us seniors are not paying any taxes on earned income. And we wonder why the federal debt keeps growing. It's really stupid. My wife and I are living in the lap of luxury and not paying taxes. Meanwhile, the debt just keeps growing.

We did not draw any more IRA money due to inflation. We've been pulling $20k out since I retired. It seems to have had no impact on our spending, yet it must have somehow. My wife does the finances. She tucks away all of her SS into bank accounts for future needs like a new car or big house emergencies like maybe a new roof. I know, it's silly to tuck money away, but she pays all the bills and takes care of the finances, so she can do what she wants. My point is that we actually live on about $62k in one of the most expensive parts of the country.


Our retirement savings are growing at 5x what we withdraw. So even if there was some catastrophic need, I don't see a problem.

I hope that helps give an idea of what retirement finance are.
Your social security payment of $56K is not earned income. Unearned Income includes Social Security benefits, pensions, State disability payments, unemployment benefits, etc. And if you had met the threshold for taxation, generally for a married couple when 1/2 of your SS benefit exceeds $32K, then it would start to be taxable. Earnings from IRAs are taxable as well. There are two circumstances I can think of where they would not be; IRA investments that lost money or they were Roth which were purchased with after tax dollars.

The popular loophole for people earning over $200K tax free are the wealthy who have extensive holdings in tax free bonds and municipals, but that's the benefit for investing in governmental projects who are big borrowers. You shouldn't have to pay tax on them.

Seniors pay taxes on earned income like everyone else. If you have guilt about living in the lap of luxury and not owing taxes, there are always needy charitable organizations that would be happy to receive your generosity. The U.S. Debt is certainly growing as the population ages faster than incoming workers, as well as Medicare, Medicaid, foreign spending, infrastructure, social spending, military spending, interest payments on the debt. You won't be able to solve it by thinking it all belongs on the backs of retired workers that paid into a system, to see those contributions go toward other programs, yet that obligation is still owed to them.

That said, I'm out of this topic, since the last one where I commented on the subject of investments got locked by Jimerson for being "political."
 
Picking up where I left off in my "Roth IRA, a really stupid idea" thread, here is the update on our 2023 tax return that may help you understand what retirement is like. It's a whole lot better than you might imagine.

For 2023, our income was $78k. That's $56k of social security, $20k IRA withdrawal, and a bit of bank interest. Federal taxes on that is $0. California tax is $0.

Yes, contrary to popular belief, the rich aren't the only ones with big loopholes. Us seniors are not paying any taxes on earned income. And we wonder why the federal debt keeps growing. It's really stupid. My wife and I are living in the lap of luxury and not paying taxes. Meanwhile, the debt just keeps growing.

We did not draw any more IRA money due to inflation. We've been pulling $20k out since I retired. It seems to have had no impact on our spending, yet it must have somehow. My wife does the finances. She tucks away all of her SS into bank accounts for future needs like a new car or big house emergencies like maybe a new roof. I know, it's silly to tuck money away, but she pays all the bills and takes care of the finances, so she can do what she wants. My point is that we actually live on about $62k in one of the most expensive parts of the country.


Our retirement savings are growing at 5x what we withdraw. So even if there was some catastrophic need, I don't see a problem.

I hope that helps give an idea of what retirement finance are.

Out of curiosity, do you recommend a good retirement savings calculator?

I have been using the AARP retirement savings calculator: https://www.aarp.org/retirement/ret...OnEEKviQSWrTAOvWKtIaAmHlEALw_wcB&gclsrc=aw.ds

But I'm wondering if there may be a better one. What do you think?
 
Your social security payment of $56K is not earned income. Unearned Income includes Social Security benefits, pensions, State disability payments, unemployment benefits, etc. And if you had met the threshold for taxation, generally for a married couple when 1/2 of your SS benefit exceeds $32K, then it would start to be taxable. Earnings from IRAs are taxable as well. There are two circumstances I can think of where they would not be; IRA investments that lost money or they were Roth which were purchased with after tax dollars.

Yes, I mis-spoke; it is unearned income. But the point I'm making is we paid no tax on our IRA withdrawal nor our SS benefits. That's $78k tax free. It's nuts.

The popular loophole for people earning over $200K tax free are the wealthy who have extensive holdings in tax free bonds and municipals, but that's the benefit for investing in governmental projects who are big borrowers. You shouldn't have to pay tax on them..

But I'm saying seniors don't need loopholes to not pay taxes. I filed a simple tax return that took nothing but the standard deduction and we paid no tax.

If you have guilt about living in the lap of luxury and not owing taxes, there are always needy charitable organizations that would be happy to receive your generosity. .

Indeed, we have two local charities that we are fond of.
 
Out of curiosity, do you recommend a good retirement savings calculator?

I have been using the AARP retirement savings calculator: https://www.aarp.org/retirement/reti...B&gclsrc=aw.ds

But I'm wondering if there may be a better one. What do you think?

No, I don't like that calculator at all. It gives no information about how it arrived at the number it came up with . Echh. I did my own spreadsheets for lots of these kinds of analysis. It's much more visual and makes you feel more comfortable with the numbers. After all, you have to make assumptions about inflation, stock market performance, interest rates, needed income. I looked for one of my old spreadsheets, but can't find it. But I made a partial one just now to give you an idea how to do it.

I used the average inflation rate and Dow performance for the last 30 years. It has a place in it where you can change those numbers to see how your savings behave with different assumptions. It's fun to play with this sort of thing because it gives you more confidence in the numbers; especially if you use conservative returns etc.

You could add a column for income needs. But remember, your needs during retirement are much less. No payroll taxes, no or minimal debt, no more need to save in IRA or 401k, etc. We need way less in retirement than we did when I was working. It's quite surprising.

[TD="align: left"] age [/TD]
[TD="align: left"] 401k contribution [/TD]
[TD="align: left"] 401k value [/TD]
[TD="align: left"] IRA contribution [/TD]
[TD="align: left"] IRA value [/TD]
[TD="align: left"] other savings [/TD]
[TD="align: left"] Other savings value [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]

[TD="align: right"] 35 [/TD]
[TD="align: right"] 5000 [/TD]
[TD="align: right"] 5000 [/TD]
[TD="align: right"] 1000 [/TD]
[TD="align: right"] 1000 [/TD]
[TD="align: right"] 500 [/TD]
[TD="align: right"] 500 [/TD]
[TD="bgcolor: #000000, align: left"] Inflation rate [/TD]
[TD="bgcolor: #000000, align: right"] 0.0225 [/TD]

[TD="align: right"] 36 [/TD]
[TD="align: right"] 5112.5 [/TD]
[TD="align: right"] 10679 [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="bgcolor: #000000, align: left"] interest rate [/TD]
[TD="bgcolor: #000000, align: left"] [/TD]

[TD="align: right"] 37 [/TD]
[TD="align: right"] 5228 [/TD]
[TD="align: right"] 17,116 [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="bgcolor: #000000, align: left"] Dow Jones Return [/TD]
[TD="bgcolor: #000000, align: right"] 0.1133 [/TD]

[TD="align: right"] 38 [/TD]
[TD="align: right"] 5345 [/TD]
[TD="align: right"] 24,401 [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]

[TD="align: right"] 39 [/TD]
[TD="align: right"] 5465 [/TD]
[TD="align: right"] 32,631 [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]

[TD="align: right"] 40 [/TD]
[TD="align: right"] 5588 [/TD]
[TD="align: right"] 41,916 [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]

[TD="align: right"] 41 [/TD]
[TD="align: right"] 5714 [/TD]
[TD="align: right"] 52,380 [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]

[TD="align: right"] 42 [/TD]
[TD="align: right"] 5843 [/TD]
[TD="align: right"] 64,157 [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]

[TD="align: right"] 43 [/TD]
[TD="align: right"] 5974 [/TD]
[TD="align: right"] 77,400 [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]

[TD="align: right"] 44 [/TD]
[TD="align: right"] 6109 [/TD]
[TD="align: right"] 92,278 [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]

[TD="align: right"] 45 [/TD]
[TD="align: right"] 6246 [/TD]
[TD="align: right"] 108,979 [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]

[TD="align: right"] 46 [/TD]
[TD="align: right"] 6387 [/TD]
[TD="align: right"] 127,713 [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]

[TD="align: right"] 47 [/TD]
[TD="align: right"] 6530 [/TD]
[TD="align: right"] 148,713 [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]

[TD="align: right"] 48 [/TD]
[TD="align: right"] 6677 [/TD]
[TD="align: right"] 172,240 [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]

[TD="align: right"] 49 [/TD]
[TD="align: right"] 6827 [/TD]
[TD="align: right"] 198,582 [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]

[TD="align: right"] 50 [/TD]
[TD="align: right"] 6981 [/TD]
[TD="align: right"] 228,062 [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]

[TD="align: right"] 51 [/TD]
[TD="align: right"] 7138 [/TD]
[TD="align: right"] 261,040 [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]

[TD="align: right"] 52 [/TD]
[TD="align: right"] 7299 [/TD]
[TD="align: right"] 297,914 [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]

[TD="align: right"] 53 [/TD]
[TD="align: right"] 7463 [/TD]
[TD="align: right"] 339,131 [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]

[TD="align: right"] 54 [/TD]
[TD="align: right"] 7631 [/TD]
[TD="align: right"] 385,185 [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]

[TD="align: right"] 55 [/TD]
[TD="align: right"] 7803 [/TD]
[TD="align: right"] 436,629 [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]

[TD="align: right"] 56 [/TD]
[TD="align: right"] 7978 [/TD]
[TD="align: right"] 494,078 [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]

[TD="align: right"] 57 [/TD]
[TD="align: right"] 8158 [/TD]
[TD="align: right"] 558,214 [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]

[TD="align: right"] 58 [/TD]
[TD="align: right"] 8341 [/TD]
[TD="align: right"] 629,801 [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]

[TD="align: right"] 59 [/TD]
[TD="align: right"] 8529 [/TD]
[TD="align: right"] 709,686 [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]

[TD="align: right"] 60 [/TD]
[TD="align: right"] 8721 [/TD]
[TD="align: right"] 798,815 [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]

[TD="align: right"] 61 [/TD]
[TD="align: right"] 8917 [/TD]
[TD="align: right"] 898,237 [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]

[TD="align: right"] 62 [/TD]
[TD="align: right"] 9118 [/TD]
[TD="align: right"] 1,009,125 [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
 
Last edited:
I added a column for income adjustment by year for inflation and I extended the 401k. I'd say you need 50-70% of what your earn when you are working. So in this example, the person started with an income of $80k and with inflation, it went to $145k at 63. Is it right? Well, based on inflation averages, yes. But who knows. You can plug in your own inflation estimate.

[TD="align: left"] age [/TD]
[TD="align: left"] 401k contribution [/TD]
[TD="align: left"] 401k value [/TD]
[TD="align: left"] IRA contribution [/TD]
[TD="align: left"] IRA value [/TD]
[TD="align: left"] other savings [/TD]
[TD="align: left"] Other savings value [/TD]
[TD="align: left"] income [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]

[TD="align: right"] 35 [/TD]
[TD="align: right"] 5000 [/TD]
[TD="align: right"] 5000 [/TD]
[TD="align: right"] 1000 [/TD]
[TD="align: right"] 1000 [/TD]
[TD="align: right"] 500 [/TD]
[TD="align: right"] 500 [/TD]
[TD="align: right"] 80000 [/TD]
[TD="bgcolor: #000000, align: left"] Inflation rate [/TD]
[TD="bgcolor: #000000, align: right"] 0.0225 [/TD]

[TD="align: right"] 36 [/TD]
[TD="align: right"] 5112.5 [/TD]
[TD="align: right"] 10679 [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: right"] 81800 [/TD]
[TD="bgcolor: #000000, align: left"] interest rate [/TD]
[TD="bgcolor: #000000, align: left"] [/TD]

[TD="align: right"] 37 [/TD]
[TD="align: right"] 5228 [/TD]
[TD="align: right"] 17,116 [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: right"] 83641 [/TD]
[TD="bgcolor: #000000, align: left"] Dow Jones Return [/TD]
[TD="bgcolor: #000000, align: right"] 0.1133 [/TD]

[TD="align: right"] 38 [/TD]
[TD="align: right"] 5345 [/TD]
[TD="align: right"] 24,401 [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: right"] 85522 [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]

[TD="align: right"] 39 [/TD]
[TD="align: right"] 5465 [/TD]
[TD="align: right"] 32,631 [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: right"] 87447 [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]

[TD="align: right"] 40 [/TD]
[TD="align: right"] 5588 [/TD]
[TD="align: right"] 41,916 [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: right"] 89414 [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]

[TD="align: right"] 41 [/TD]
[TD="align: right"] 5714 [/TD]
[TD="align: right"] 52,380 [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: right"] 91426 [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]

[TD="align: right"] 42 [/TD]
[TD="align: right"] 5843 [/TD]
[TD="align: right"] 64,157 [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: right"] 93483 [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]

[TD="align: right"] 43 [/TD]
[TD="align: right"] 5974 [/TD]
[TD="align: right"] 77,400 [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: right"] 95586 [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]

[TD="align: right"] 44 [/TD]
[TD="align: right"] 6109 [/TD]
[TD="align: right"] 92,278 [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: right"] 97737 [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]

[TD="align: right"] 45 [/TD]
[TD="align: right"] 6246 [/TD]
[TD="align: right"] 108,979 [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: right"] 99936 [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]

[TD="align: right"] 46 [/TD]
[TD="align: right"] 6387 [/TD]
[TD="align: right"] 127,713 [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: right"] 102185 [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]

[TD="align: right"] 47 [/TD]
[TD="align: right"] 6530 [/TD]
[TD="align: right"] 148,713 [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: right"] 104484 [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]

[TD="align: right"] 48 [/TD]
[TD="align: right"] 6677 [/TD]
[TD="align: right"] 172,240 [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: right"] 106835 [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]

[TD="align: right"] 49 [/TD]
[TD="align: right"] 6827 [/TD]
[TD="align: right"] 198,582 [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: right"] 109239 [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]

[TD="align: right"] 50 [/TD]
[TD="align: right"] 6981 [/TD]
[TD="align: right"] 228,062 [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: right"] 111697 [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]

[TD="align: right"] 51 [/TD]
[TD="align: right"] 7138 [/TD]
[TD="align: right"] 261,040 [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: right"] 114210 [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]

[TD="align: right"] 52 [/TD]
[TD="align: right"] 7299 [/TD]
[TD="align: right"] 297,914 [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: right"] 116779 [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]

[TD="align: right"] 53 [/TD]
[TD="align: right"] 7463 [/TD]
[TD="align: right"] 339,131 [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: right"] 119407 [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]

[TD="align: right"] 54 [/TD]
[TD="align: right"] 7631 [/TD]
[TD="align: right"] 385,185 [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: right"] 122094 [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]

[TD="align: right"] 55 [/TD]
[TD="align: right"] 7803 [/TD]
[TD="align: right"] 436,629 [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: right"] 124841 [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]

[TD="align: right"] 56 [/TD]
[TD="align: right"] 7978 [/TD]
[TD="align: right"] 494,078 [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: right"] 127650 [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]

[TD="align: right"] 57 [/TD]
[TD="align: right"] 8158 [/TD]
[TD="align: right"] 558,214 [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: right"] 130522 [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]

[TD="align: right"] 58 [/TD]
[TD="align: right"] 8341 [/TD]
[TD="align: right"] 629,801 [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: right"] 133459 [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]

[TD="align: right"] 59 [/TD]
[TD="align: right"] 8529 [/TD]
[TD="align: right"] 709,686 [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: right"] 136461 [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]

[TD="align: right"] 60 [/TD]
[TD="align: right"] 8721 [/TD]
[TD="align: right"] 798,815 [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: right"] 139532 [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]

[TD="align: right"] 61 [/TD]
[TD="align: right"] 8917 [/TD]
[TD="align: right"] 898,237 [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: right"] 142671 [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]

[TD="align: right"] 62 [/TD]
[TD="align: right"] 9118 [/TD]
[TD="align: right"] 1,009,125 [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: right"] 145881 [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]

[TD="align: right"] 63 [/TD]
[TD="align: right"] 9323 [/TD]
[TD="align: right"] 1,132,782 [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: right"] 145881 [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]

[TD="align: right"] 64 [/TD]
[TD="align: right"] 9532 [/TD]
[TD="align: right"] 1,270,658 [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]

[TD="align: right"] 65 [/TD]
[TD="align: right"] 9747 [/TD]
[TD="align: right"] 1,424,371 [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]

[TD="align: right"] 66 [/TD]
[TD="align: right"] 9966 [/TD]
[TD="align: right"] 1,595,718 [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]

[TD="align: right"] 67 [/TD]
[TD="align: right"] 10191 [/TD]
[TD="align: right"] 1,786,704 [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]

[TD="align: right"] 68 [/TD]
[TD="align: right"] 10420 [/TD]
[TD="align: right"] 1,999,557 [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]

[TD="align: right"] 69 [/TD]
[TD="align: right"] 10654 [/TD]
[TD="align: right"] 2,236,761 [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]

[TD="align: right"] 70 [/TD]
[TD="align: right"] 10894 [/TD]
[TD="align: right"] 2,501,080 [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
[TD="align: left"] [/TD]
 
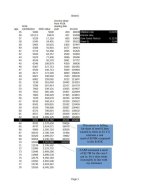
I never did give you what you wanted. Here is another spreadsheet that shows the income draw you would have based on your retirement savings. I assumed the usual 4% draw, but you can use whatever you want. You can compare the draw to the estimated income need. My notes may be hard to follow.
 

Attachments

  • retirement calculator.jpg
    retirement calculator.jpg
    56.2 KB · Views: 0
thanks, Paul. lots of food for thought here. on the AARP calculator they show some of their variables when you click "view and edit economic assumptions." looks like this:

wAAACH5BAEKAAAALAAAAAABAAEAAAICRAEAOw==


it's all quite a moving target when you consider inflation, cost of living, ROI, life expectancy... I think social security is a very good thing for society​
 
Well, I don't have any fancy spreadsheets or formulas, but here's my retirement plan, and it has worked very well. I'm not officially retired yet, but getting closer to throwing in the towel every month.

1) Work hard and earn as much as I can every year.
2) Don't spend everything I earn.
3) Invest everything I don't need to spend . . . and watch it grow year after year.
4) Spend whatever I need to spend in order to have a comfortable life for me and my family (there's no reason to live like paupers).
5) Don't piss away money on exotic vacations, extravagant weddings, lottery tickets, gambling, or eating out more than a couple of times a month.
6) Don't go into debt unless it is for business equipment (that will earn back more money) or a home. No other exceptions.
7) Make sure I am well-insured to avoid major healthcare expenses, fire, home, and auto.
8) Have plenty of term life insurance coverage to take care of the family in case I should croak unexpectedly.
9) Pay off the mortgage as quickly as possible -- and then start investing that money instead.
10) Create some revenue streams that will continue bringing in cash even after I stop working.

I can safely say that right now I could retire, continue my exact same lifestyle, and never run out of money before I die unless the whole economy collapses.
 
Ok, I didn't see that.

btw why does everyone base retirement income targets on working-age income rather than working-age expenses? what if you have a very high savings rate while you're working? surely you just need to worry about continuing to pay your expenses
 
Well, I don't have any fancy spreadsheets or formulas, but here's my retirement plan, and it has worked very well. I'm not officially retired yet, but getting closer to throwing in the towel every month.

1) Work hard and earn as much as I can every year.
2) Don't spend everything I earn.
3) Invest everything I don't need to spend . . . and watch it grow year after year.
4) Spend whatever I need to spend in order to have a comfortable life for me and my family (there's no reason to live like paupers).
5) Don't piss away money on exotic vacations, extravagant weddings, lottery tickets, gambling, or eating out more than a couple of times a month.
6) Don't go into debt unless it is for business equipment (that will earn back more money) or a home. No other exceptions.
7) Make sure I am well-insured to avoid major healthcare expenses, fire, home, and auto.
8) Have plenty of term life insurance coverage to take care of the family in case I should croak unexpectedly.
9) Pay off the mortgage as quickly as possible -- and then start investing that money instead.
10) Create some revenue streams that will continue bringing in cash even after I stop working.

I can safely say that right now I could retire, continue my exact same lifestyle, and never run out of money before I die unless the whole economy collapses.

This sort of sounds like you comfortably overshot the mark so you didn't need to worry about it. Which is great, but I'd like to have accurate targets and estimates if I could, especially since my last 10% of income is probably the most burdensome both in being the hardest/least desirable workdays and also making life in general more difficult by preventing R&R. And since my kids are only going to be small once, this is a particularly valuable period for spending time with family.

If I knew I were overshooting the mark, I would work less and I possibly would have bought a larger/newer house. I tend to err on the side of caution anyway, so maybe it's a moot point... I'd rather do my financial planning around estimated income in case of recession/client losses... So I might just keep my expenses as trim as possible in case of calamity. And then excess earnings will just go to savings. But it would sting a bit to get to retirement with way more than I need and think to myself that we could have bought a newer house and my wife wouldn't have had to worry so much about lead paint...

Conversely, what if I'm saving way too little... better bust my ass to beef up business...
 
btw why does everyone base retirement income targets on working-age income rather than working-age expenses? what if you have a very high savings rate while you're working? surely you just need to worry about continuing to pay your expenses

And why assume expenses will go down when you stop working? The less you work . . . the more time you have to spend. I came to that conclusion clear back in high school. The more I worked, the less time I had to go out and fritter it away, and then the savings accumulated much faster. After you retire, you might want to spend more on travel, charity, lifting up other people in your extended family, etc. With the exception of business insurance and some other minor fees and subscriptions I don't really see my expenses dropping very much.
 
Conversely, what if I'm saving way too little... better bust my ass to beef up business...

Work now, work hard, work smart. That is my mantra. You know the old saying, "make hay while the sun shines".

There's nothing wrong with your approach if it works for you, but it seems a lot like an athlete who doesn't want to put 100% into their effort if 90% will be enough to win the race or get on the podium. I almost always throw 100% of my effort into whatever it is, regardless of whether 100% was really needed or not. I don't need tables or spreadsheets to plan things down to the nickle because I'm not trying to squeak by. I want to overshoot. That is where peace of mind comes from. Plus the freedom later to say no to **** you don't want to work on.

I used to work with a shooter in Boston who told me, when I was in a jam, that he couldn't help with a two-camera shoot the next day because it was his daughter's 2nd birthday. That told me everything I need to know about his priorities and he was the last person I ever called next time. There is a time for work, which often is beyond our control. Make hay while the sun shines. On the other hand, quality family time can come the next day or whatever. Do you think a two-year-year old can read a calendar to know if it is her birthday or not? Trust me, your family will be more secure, safer, and comfortable the more you earn. Not only when they are little, but when they want to go to college, buy a house, etc. If daddy and mommy have a bigger nest egg, they can help without it being a burden on themselves. Personally, I never took a penny from my parents once I started working at age 16 and I moved out of the house an went to college (on my own dime) as soon as I graduated from high school. But I do enjoy helping my kids over the rough spots when they need a little grease on the wheels. I'm glad I didn't need it, but I'm glad to be able to give it.

Making work a priority is making the family a priority. Think about it.

yeah, that's my dream... give my children greater security

But this is time that we can't get back. Saw a video with Michael Keaton recently where he said: "Hang out with your kids as much as you can as long as you can. You will never regret it... You're gonna lose some jobs. It's okay in the long run." https://www.tiktok.com/@feelingbluevibe/video/7139869338055527685?lang=en

I don't put a premium on which days I spend with them. I don't take off for birthdays. I work on most New Year's Eves. But when we were saving for a house and the prices kept going up, I was working 30 days a month during the busy parts of the year and that just ain't necessary on the regular.
 
Well, I don't have any fancy spreadsheets or formulas, but here's my retirement plan, and it has worked very well. I'm not officially retired yet, but getting closer to throwing in the towel every month.

1) Work hard and earn as much as I can every year.
2) Don't spend everything I earn.
3) Invest everything I don't need to spend . . . and watch it grow year after year.
4) Spend whatever I need to spend in order to have a comfortable life for me and my family (there's no reason to live like paupers).
5) Don't piss away money on exotic vacations, extravagant weddings, lottery tickets, gambling, or eating out more than a couple of times a month.
6) Don't go into debt unless it is for business equipment (that will earn back more money) or a home. No other exceptions.
7) Make sure I am well-insured to avoid major healthcare expenses, fire, home, and auto.
8) Have plenty of term life insurance coverage to take care of the family in case I should croak unexpectedly.
9) Pay off the mortgage as quickly as possible -- and then start investing that money instead.
10) Create some revenue streams that will continue bringing in cash even after I stop working.

I can safely say that right now I could retire, continue my exact same lifestyle, and never run out of money before I die unless the whole economy collapses.

A+ Doug. Exactly what we did.
 
btw why does everyone base retirement income targets on working-age income rather than working-age expenses? what if you have a very high savings rate while you're working? surely you just need to worry about continuing to pay your expenses

Yes, exactly. That's why I said retirement needs are far below your current income (adjusted for inflation). We live on way less than I made when I retired. Nothing has changed about our lifestyle. I did a spreadsheet to layout how much our expenses would be and how much we would need. I couldn't believe it was so little, but it turned out to be true.
 
I don't need tables or spreadsheets to plan things down to the nickle because I'm not trying to squeak by. I want to overshoot. That is where peace of mind comes from. Plus the freedom later to say no to **** you don't want to work on..

Why not do both? Do what your doing and check with some calculations to see how you are doing.
 
I said I wasn't going to post, but I didn't say I don't want to help. The single best thing you can do is get out from under the 30 year mortgage. Do it in 10 years, even if it means a cheaper house, 10 years goes by fast, and look at what you save in total interest paid over the loan.

Loan amt $400K @ 7.77%

30 years total interest paid = $507K; monthly payment with tax and insurance = $2,722
10 years total interest paid = $141K; monthly payment with tax and insurance = $4,269

You pocket $366K in total interest over 10 years, and you're finished with the obligation 20 years sooner. It's a 20 year head start on the rest of your life with a nice equity for a nest egg.

Next to living at home, it's a no-brainer that you and your wife can swing, for a temporary hardship that goes by quickly and your kids won't notice.
 
Back
Top